Battle of the Trend Following Indexes: August 2026
The Battle of the Trend Following Indexes is our monthly comparison of the leading trend-following benchmarks. All figures are through 31 August 2026, with each index history rebased to 1,000,000 on 1 January 2020.
August 2026 Result
August ended the losing run. All seven indexes finished positive after two consecutive negative months, and the TTU Trend Barometer recovered from 30 to 55, closing the month on the threshold of a favourable environment. The three-month sequence now reads plainly: up 23 points in June, down 25 in July, up 25 in August. June and July showed that the barometer and index returns could move in opposite directions. In August they finally moved the same way, although, as the weekly path shows, not at the same pace.
Classic Trend led at +5.3%, followed by IASG at +5.1%, TTU at +3.6%, BTOP50 at +3.0%, SG Trend and Systematic Momentum at +2.9% and SG CTA at +2.8%. The gap from best to worst widened to 2.5 percentage points from 2.0 in July. The more striking feature is how closely August inverted July. The three weakest indexes in July, IASG, Classic Trend and TTU, were the three strongest in August. BTOP50 and Systematic Momentum, first and second in July, finished fourth and joint fifth.
The ranking only partly followed the construction spectrum. At the ends it held. Classic Trend, with three constituents, led the recovery, while SG CTA, which blends pure trend with a broader systematic factor set, trailed. The middle did not follow constituent count. Two broad manager ensembles, IASG with 50 programs and TTU with 47, finished ahead of the 10-constituent SG Trend and the 20-constituent BTOP50. What August tracked more closely was the reverse of July’s order: the benchmarks that gave up most when trends failed recovered most when trends resumed. Two months are not enough to establish why. One explanation consistent with the pattern is convexity working through exposure rather than headcount, since a construction that carries trend risk in greater size, however many programs it holds, magnifies both the payoff when trends persist and the damage when they break. Differences in which markets each index happened to be positioned in could produce a similar result.
The weekly record explains why returns lagged the recovery in the environment. The barometer rose every week: 34, 39, 50 and 55. SG Trend’s month-to-date estimate did not follow in proportion: -0.75% after week one, +0.83% after week two, +1.13% after week three and +1.66% at 28 August. The week in which the barometer rose most, an 11-point gain to 50, added only about 0.3 percentage point. The week with the most markets rising, 34 of 49, lost money. The final print of +2.9% then sat more than a point above the last weekly estimate. That gap combines the final session on 31 August with any revision from daily estimate to final figure, and the published data do not separate the two. What the path does show is that the barometer recovered steadily while SG Trend’s estimated return caught up much later.
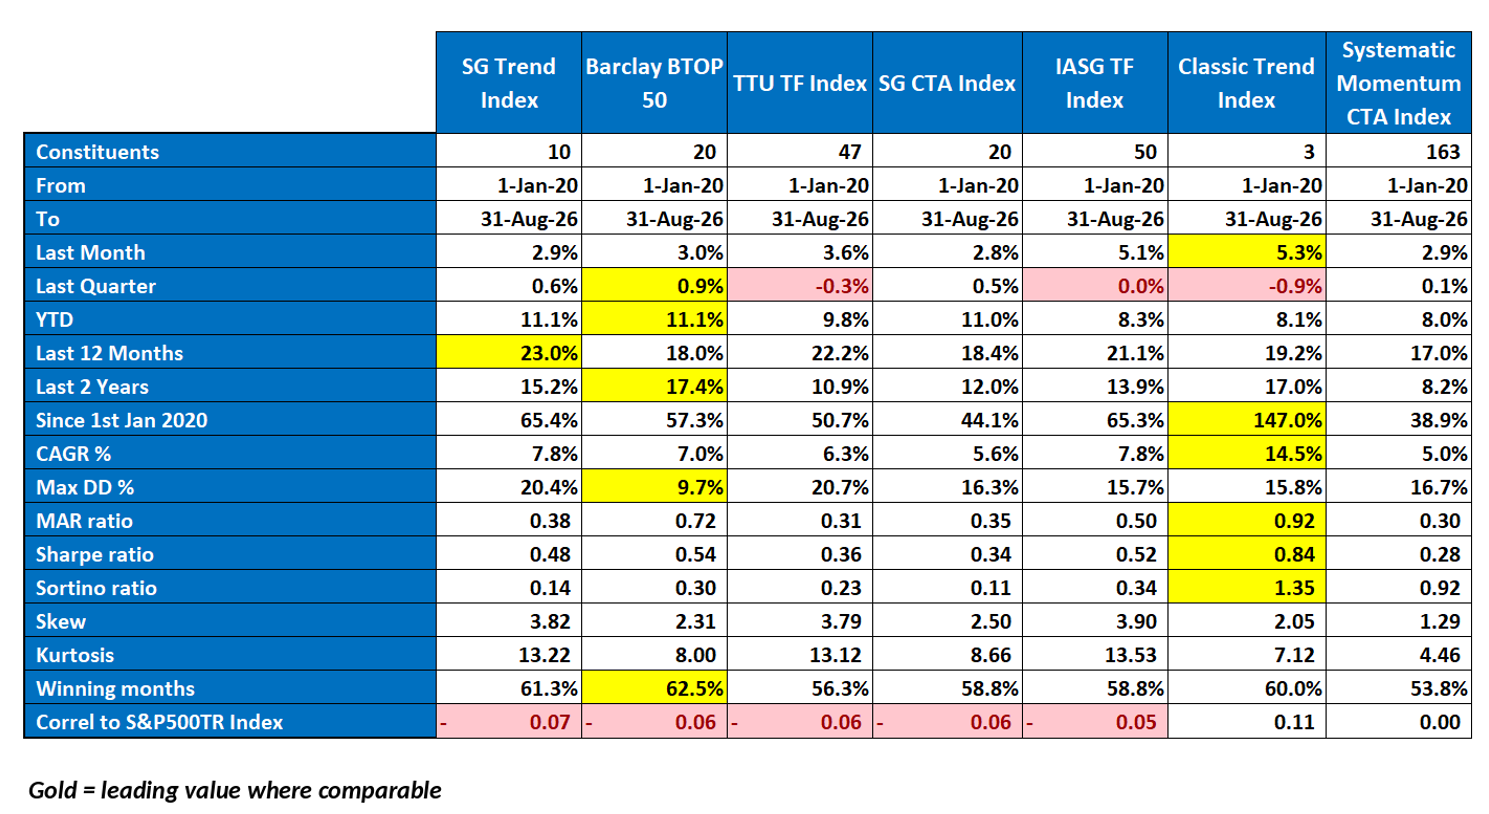
The year-to-date race tightened further at the top and compressed from below. BTOP50 and SG Trend share the lead at 11.1%, with SG CTA at 11.0%, ending its three-month run in first place by one-tenth of a point. TTU follows at 9.8%, IASG at 8.3%, Classic Trend at 8.1% and Systematic Momentum at 8.0%. The gap from first to last narrowed from 5.4 percentage points to 3.1 in a single month. Classic Trend moved off the bottom of the table and Systematic Momentum replaced it. Over the trailing quarter, June still dominates: BTOP50 leads at +0.9%, and Classic Trend is last at -0.9% with its June decline still inside the window.
The long-run hierarchy held. Classic Trend continues to lead total return, CAGR, MAR, Sharpe and Sortino since 1 January 2020. Every index’s maximum drawdown is unchanged, as a month of gains across the board would suggest. BTOP50 retains the shallowest at 9.7% and the highest share of winning months, now 62.5%. Its Last 2 Years return jumped from 11.1% to 17.4% as a losing August 2024 rolled out of the window. SG Trend remains second on total return at 65.4%, only one-tenth of a point ahead of IASG.
Performance Highlights
Here is how the seven indexes came through August:
Classic Trend Index
August: +5.3%, the strongest result in the group and a sharp reversal of its placement in June and July. Trailing quarter: -0.9%, the weakest, with June’s loss still in the window. YTD: +8.1%, up from last to sixth. Since January 2020, Classic Trend has gained 147.0% at a 14.5% CAGR, more than twice the next-highest total return. It retains the strongest MAR at 0.92, Sharpe at 0.84 and Sortino at 1.35. Maximum drawdown is unchanged at 15.8%, and its +0.11 correlation to the S&P 500 Total Return remains the only positive reading in the group.
IASG Trend Following Index
August: +5.1%, second and only 0.2 percentage point behind the leader, after finishing last in July. Trailing quarter: 0.0%. YTD: +8.3%, fifth. Since 2020, IASG has gained 65.3% at a 7.8% CAGR, level with SG Trend on CAGR and one-tenth of a point behind it on total return. Its 15.7% maximum drawdown is the second-lowest in the comparison, and its MAR of 0.50 and Sharpe of 0.52 rank third behind Classic Trend and BTOP50. The long-run columns reconcile with the restated July series this month.
TTU Trend Following Index
August: +3.6%, third. Trailing quarter: -0.3%. YTD: +9.8%, fourth. Since 2020, TTU has gained 50.7% at a 6.3% CAGR with a 20.7% maximum drawdown, still the deepest in the group. Its Last 12 Months return of 22.2% is second only to SG Trend.
Barclay BTOP50 Index
August: +3.0%, fourth. Trailing quarter: +0.9%, best of the seven. YTD: +11.1%, joint first with SG Trend and marked as the leader on unrounded figures. Since 2020, BTOP50 has gained 57.3% at a 7.0% CAGR. It holds the lowest maximum drawdown at 9.7%, the highest share of winning months at 62.5% and the strongest Last 2 Years return at 17.4%. Its MAR of 0.72 and Sharpe of 0.54 are second only to Classic Trend.
SG Trend Index
August: +2.9%. Trailing quarter: +0.6%. YTD: +11.1%, joint first. Its Last 12 Months return of 23.0% leads the group for a third straight month. Since 2020, SG Trend is up 65.4% at a 7.8% CAGR with a 20.4% maximum drawdown. The weekly estimates trace the month’s shape: -0.75% after week one, +0.83% after week two, +1.13% after week three and +1.66% at 28 August, before the final figure settled at +2.9%.
Systematic Momentum CTA Index
August: +2.9%, level with SG Trend. Trailing quarter: +0.1%. YTD: +8.0%, now last in the group, though only 0.1 percentage point behind Classic Trend. Since 2020, the index has gained 38.9% at a 5.0% CAGR with a 16.7% maximum drawdown. Its Sortino of 0.92 remains second-highest among the seven, and its correlation to the S&P 500 Total Return is 0.00. Its wide constituent base, which cost little in July’s scattered losses, delivered close to the peer median in August’s recovery.
SG CTA Index
August: +2.8%, the smallest gain in the group. Trailing quarter: +0.5%. YTD: +11.0%, third, surrendering the lead it had held for three months by 0.1 percentage point. Since 2020, the index has gained 44.1% at a 5.6% CAGR with a 16.3% maximum drawdown. Its Sortino of 0.11 is the lowest of the seven and its Sharpe of 0.34 sits in the lower half, consistent with a construction that reaches beyond pure trend into a broader systematic universe.
Performance Snapshot
The table below compares the seven trend-following indexes through 31 August 2026. Gold highlights the leading values where a clear performance comparison is useful.
Performance Since 1 January 2020
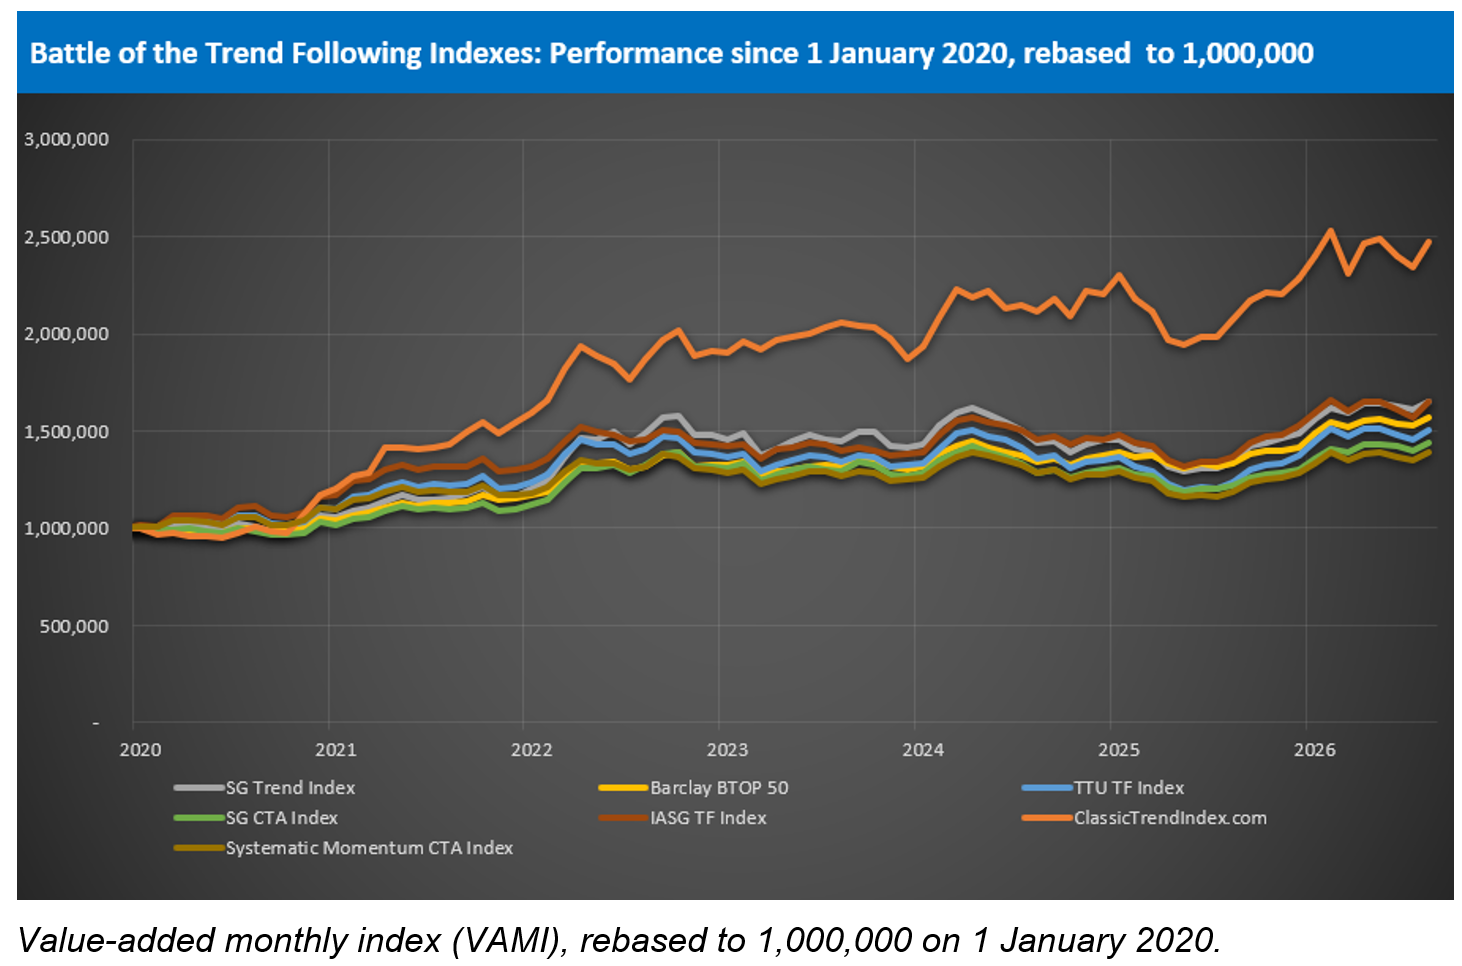
The chart below plots the value-added monthly index (VAMI) for all seven benchmarks, rebased to 1,000,000 on 1 January 2020. Classic Trend remains well clear of the peer group over the full period, and August’s recovery is visible at the right-hand edge, lifting it back toward its February peak. Beneath it, SG Trend and IASG have converged at the top of the peer cluster.
Performance Commentary
Classic Trend Index
Classic Trend returned +5.3% in August and climbs from last to sixth on YTD at +8.1%. After two losing months, the index recovered faster than the rest of the group once trends began to hold. Across July and August combined, Classic Trend is up roughly 3.0%, ahead of every other index over the two months. The trailing-quarter figure of -0.9% remains the weakest because June’s loss still sits inside the window, a reminder that the quarter column currently reflects June more than August.
IASG Trend Following Index
IASG returned +5.1% in August, close behind Classic Trend, after finishing last in July at -2.6%. Seventh to second in a single month is the joint-largest move in the table, matched only by Classic Trend. It cautions against reading IASG’s July result as a verdict on the index. On the restated series, IASG now sits level with SG Trend on CAGR at 7.8% and one-tenth of a point behind it on total return, while holding the second-lowest maximum drawdown in the group.
TTU Trend Following Index
TTU gained 3.6% in August, bringing its year-to-date return to 9.8%. After losing more than most of its peers in July, it recovered to third place. June and July tested the limits of manager diversification as markets first moved against established positions, then reversed before new trends could mature. August brought more persistent moves in Grains, Energy, Meats and the VIX. Across its 47 programs, TTU had several possible ways to participate in that recovery.
Barclay BTOP50 Index
BTOP50 returned +3.0% in August, fourth in the comparison, after leading July’s defensive table. It now shares the YTD lead at +11.1% and leads the trailing quarter at +0.9%. The index is an equally weighted, annually rebalanced selection of the largest investable CTA programs, and that diversification across managers lost least in July and captured a middling share of August’s recovery. Its Last 2 Years return of 17.4% leads outright after a losing August 2024 rolled out of the window. Across the full three-month stretch of two losses and a recovery, it is the best-placed index in the group.
SG Trend Index
SG Trend returned +2.9% in August, shares the YTD lead at +11.1% and holds the twelve-month lead at +23.0% for a third straight month. Its weekly estimates give the clearest view of how August’s return was assembled. The index was -0.75% after week one, even as 34 of 49 markets rose and Metals swept higher, with most of the largest gains coming in markets that had been falling. It improved to +0.83% in week two as Energy reversed and Grains strengthened, edged to +1.13% in week three despite the barometer’s 11-point jump, and reached +1.66% at 28 August as Grains extended into chart highs. The final figure of +2.9% sits more than a point above that last estimate, a gap that combines the 31 August session with any revision to the daily estimates.
Systematic Momentum CTA Index
Systematic Momentum returned +2.9% in August and now sits last on YTD at +8.0%, though the bottom four are separated by only 1.8 percentage points. In July, its 163 constituents diluted scattered, idiosyncratic errors and the index lost little. In August, the same spread of constituents diluted the recovery, delivering a return close to the peer median. The two months are consistent with a wide constituent base narrowing outcomes in both directions. Its 0.00 correlation to the S&P 500 Total Return remains the most neutral reading in the comparison.
SG CTA Index
SG CTA returned +2.8% in August, the smallest gain in the group, and slips to third on YTD at +11.0%. Last month we noted that SG CTA had led the losing stretch by participating less rather than capturing more, and that the same structural choice could work the other way once persistent trends returned. August was the first test of that. It trailed, but only modestly, finishing 0.1 point behind SG Trend. Its Last 12 Months return of 18.4% and Sortino of 0.11 remain toward the bottom of the comparison.
August Market Narrative
August was a month of repair. The TTU Trend Barometer read 34, 39, 50 and 55 across the four weeks ending in August, rising every week and reaching the 55% boundary of a favourable environment for the first time in the sequence. The count of markets finishing each week higher moved the other way: 34, 31, 31 and 21 of 49. The barometer peaked in the week with the fewest markets rising. That divergence is the thread through the month. The two measures count different things. The first records how many markets closed the week higher. The barometer records how many are generating medium-to-strong trends, in either direction. As August progressed, fewer markets rose while more of the moves on the board extended structures already in place, and SG Trend’s estimated return tracked the second measure more closely than the first.
Week ending 7 August: Metals sweep the board and the index slips
The first week produced the broadest advance of the month. Metals led at +6.52% with all five contracts higher, Silver up 9.89% and Gold 7.13%. Equity Indices rose 3.61% with all seven contracts higher, most at or near new highs. Sugar broke out of a range held since spring with a 12.21% gain, the largest move on the board, while Orange Juice fell 8.00% after leading the previous week. Energy fell furthest at -3.95%, with WTI down 7.67% as July’s failed breakout became a decline of its own. The number of markets rising jumped to 34 of 49 from 24, and the barometer recovered 4 points to 34. SG Trend nevertheless opened August at -0.75%. The precious metals were rising inside declines that had run since February, and Bonds rallied against two weeks of falling. Only Energy’s continued fall and the equity advance paid an existing book.
Week ending 14 August: Energy snaps back and the index turns up
Week two was narrower but paid. Energy led at +5.33% with all six contracts higher and Heating Oil up 9.75%, reversing the sector’s two-week decline. Grains gained 2.66% with seven of eight contracts higher. The previous week’s young moves mostly failed their first test. Metals went flat at -0.05% and Cocoa reversed from +6.83% to -2.07%. The established moves kept working. Equity Indices rose for a fourth week, Meats fell for a third and the VIX for a fourth, down 8.43%. Markets rising slipped to 31 of 49, yet the barometer rose 5 points to 39 and its 10-day rate of change turned positive for the first time since the late-July collapse. SG Trend improved to +0.83% for the month, a weekly gain of roughly 1.6%. Most of the payoff came from continuations rather than from the week’s largest reversal.
Week ending 21 August: Amplitude doubles and the barometer jumps 11 points
The third week was the largest of the month in scale. Four commodity sectors advanced together: Energy 4.43%, Metals 4.33%, Soft Commodities 3.79% and Grains 1.97%. Bitcoin jumped 21.86%, the largest single move on the board by a wide margin. Equity Indices fell 1.87% with all seven contracts lower, ending a four-week advance. The number of markets rising was unchanged at 31 of 49, but the average move across the board more than doubled from 0.80% to 1.97%, and the barometer jumped 11 points to 50, back into Neutral territory. SG Trend added only about 0.3 percentage point to reach +1.13%. Much of the week’s distance ran against established structure. Bitcoin rallied inside a decline in place since the start of the year, Platinum, Silver and Gold recovered ground without reclaiming their February highs. Of the ten largest moves on the board, only three extended something already running.
Week ending 28 August: The quietest week reaches the threshold
Week four inverted the third. Grains supplied almost all of the movement, up 5.63% with all eight contracts higher, Wheat up 12.12% and seven contracts at or near chart highs. Almost everything else was small. Energy gave back 1.57%, Metals 0.72% and Bitcoin 1.64% as the prior week’s counter-trend rallies stopped and the structures beneath them resumed. Meats fell for a fifth week and the VIX for a sixth. Markets rising fell sharply to 21 of 49, and the average move collapsed from 1.97% to 0.43%. Yet the barometer added 5 points to reach 55, the highest reading of the sequence, and SG Trend rose to +1.66%. The reason was composition. Eight of the ten largest moves extended a structure already in place, against three the week before.
31 August: The final session
The last trading day of August fell inside the week reported on 4 September, so the weekly sector data cannot isolate it. The index figures show the size of the gap, but not its source. SG Trend’s estimate stood at +1.66% on 28 August, and the published August return is +2.9%. The roughly 1.2-point gap combines the final session with any revision from daily estimate to final figure, and the published data do not separate the two. The week that followed was dominated by Energy, up 5.95% with all six contracts higher and both crude contracts up more than 9%, while the barometer held at 55. If a meaningful share of the gap came from the final session, the opening of that move is a plausible source. Either way, the largest single step in SG Trend’s reported August figure came after the barometer had finished rising.
Implications for Index Construction and August Capture
June’s losses came from transition, and July’s from a succession of trends that died before they matured. August was the first month in the sequence in which trends survived long enough to be held. Grains extended across three weeks into chart highs. The VIX fell for six consecutive weeks and the Meats for five. Once moves persisted, dispersion widened from 2.0 to 2.5 percentage points and the ranking changed markedly.
The near-inversion of July’s order is the most useful observation for allocators. The indexes that lost most in July gained most in August. Over July and August combined, the seven indexes are separated by only 1.5 percentage points, from roughly +3.0% for Classic Trend to +1.5% for SG CTA. Read one month at a time, the table swings between apparent winners and losers. Read in pairs, it gives a steadier picture of how each construction behaves across a loss and a recovery, although two months remain a small sample from which to attribute cause. What the pairing does establish is that a single monthly rank can change quickly and says relatively little about index quality on its own.
The second lesson concerns timing. The weekly relationship between the reading and returns was erratic throughout: a 4-point rise with a loss, a 5-point rise with a gain of about 1.6%, an 11-point rise with about 0.3% and a 5-point rise with about 0.5%. Trend strength describes the persistence available in markets. Returns depend on whether portfolios already hold positions in the markets where that persistence appears. July showed that the two measures are not synchronous. In August the environment reading led and SG Trend’s estimated return caught up later, although how much of the late gain reflects the final session rather than revision cannot be determined from the published figures.
Closing Reflection
August ended a two-month losing run with gains for all seven indexes, a 25-point recovery in the barometer to the 55% threshold and a near-inversion of July’s ranking. Classic Trend led at +5.3% and IASG followed at +5.1%, the two weakest indexes in July. BTOP50 and SG Trend share the YTD lead at 11.1%, with SG CTA one-tenth of a point behind. SG Trend retains the twelve-month lead at 23.0%, BTOP50 the lowest drawdown at 9.7%, and Classic Trend the long-horizon return and return-to-volatility statistics shown here.
July’s lesson was that the characteristics separating these indexes need persistent trends before they become visible. August supplied some persistence, in Grains, Energy and the long decline in volatility, and the spread between the indexes widened again. The indexes that lost most in July recovered most in August, while SG CTA, which blends trend with other systematic strategies, recovered least. Whether that reflects structural trend exposure or the particular markets each index held over these two months, the spread was organised in a way July’s was not.
The month also clarified how the environment and returns relate. The barometer recovered steadily across four weeks, while SG Trend’s estimated return caught up much later. For allocators reading the table monthly, the June to August sequence argues for evaluating these benchmarks across a full loss-and-recovery cycle rather than any single month within it. On that basis, the trailing-quarter range between the seven indexes is 1.8 percentage points, narrower than the spread in any one of the three months that make it up.
About the Indexes
- SG Trend Index
Created by Société Générale, the SG Trend Index represents the largest trend-following CTA programs, focusing on systematic strategies with significant AUM. It captures broad market movements across various assets. More on SG Trend Index - Barclay BTOP50 Index
Managed by BarclayHedge, this index follows the largest investable CTAs, emphasizing diversification across major futures markets. It’s a widely referenced benchmark for managed futures. More on BTOP50 Index - TTU Trend Following Index
Developed by Top Traders Unplugged, the TTU TF Index includes programs with a 15-year track record, emphasizing resilience through experience and diversification across a large ensemble of programs. More on TTU TF Index - SG CTA Index
Another index by Société Générale, the SG CTA Index covers a broader array of CTA strategies, providing insight into the managed futures landscape beyond trend following alone. More on SG CTA Index - IASG Trend Following Index
This index, managed by IASG, tracks CTAs that primarily use trend-following strategies, offering a focused benchmark within the managed futures space. More on IASG TF Index - Classic Trend Index
The Classic Trend Index, curated by the Aussie Turtles, is a benchmark for traditional trend-following strategies, focusing on consistent, systematic approaches across diversified asset classes. More on Classic Trend Index - Systematic Momentum CTA Index
Managed by NilssonHedge, this index tracks CTAs focused on momentum-based strategies, providing a purist view of momentum trading within managed futures. More on Systematic Momentum CTA Index
Stay tuned for next month’s Battle of the Trend Following Indexes to see which benchmarks emerge as the top performers in the trend-following landscape.
Get the Aussie Turtles® Trend Following Guide
If you want to go deeper into the principles behind trend following and build a process that survives real market conditions, the Aussie Turtles® Trend Following Guide is now available on Amazon.
This book is a field manual for traders who want to move beyond prediction and commit to disciplined, systematic practice. Written by Adam Havryliv and Richard Brennan, it distills decades of experience into a practical and philosophical framework for navigating complex markets.
The guide challenges the myths of consistency and control. It explains why markets evolve through trader impact, serial correlation, and emergent structure rather than forecasts. It does not promise a holy grail system. Instead, it teaches the mindset required to capture the rare asymmetric outliers that drive long term performance.
If you are ready to trade with clarity, resilience, and conviction, this is the place to start. Click on the image below.